When the investment climate and supply capacity jointly determine project decisions
Our latest Market Insights survey of 326 IT service providers, system houses, and system integrators in Germany and Austria shows that business sentiment in the IT channel has deteriorated compared to the same period last year.
Instead of growth drivers, defensive investment decisions by end customers are dominating—with direct consequences for sales, portfolio prioritization, and partner strategies at Vendor.
Economic Situation: Market Remains Under Pressure, Stability Prevails
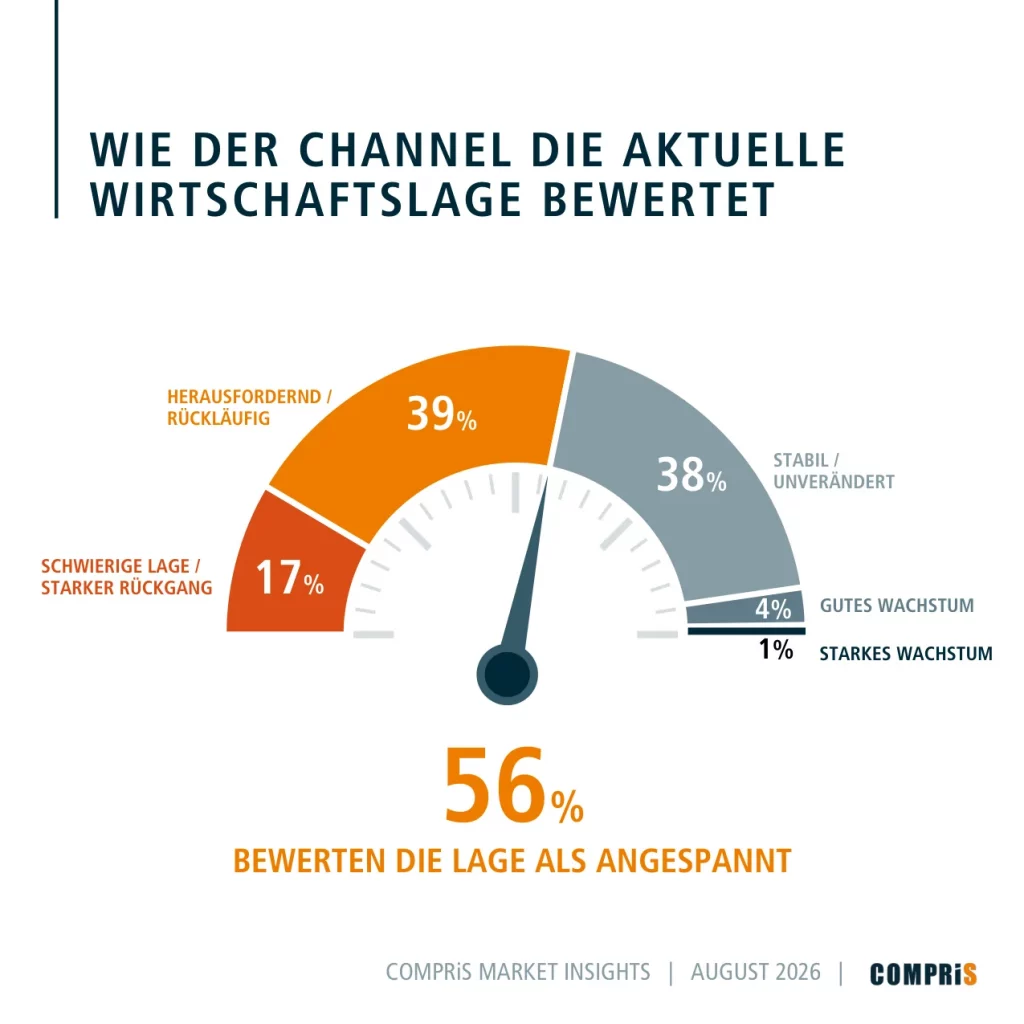
39% describe the current economic situation as challenging or in decline.
38% view it as stable and unchanged.
17% are already describing the situation as difficult, with a sharp decline.
Only 4% report growth, and just 1% report strong growth.
Overall, 56% of respondents view the current situation negatively. At the same time, it is noteworthy that 38% continue to view their business situation as stable. The results reveal a market that is under pressure but has not yet fallen into a widespread sense of crisis.
Year-over-year comparison: Sentiment is significantly more cautious than it was twelve months ago
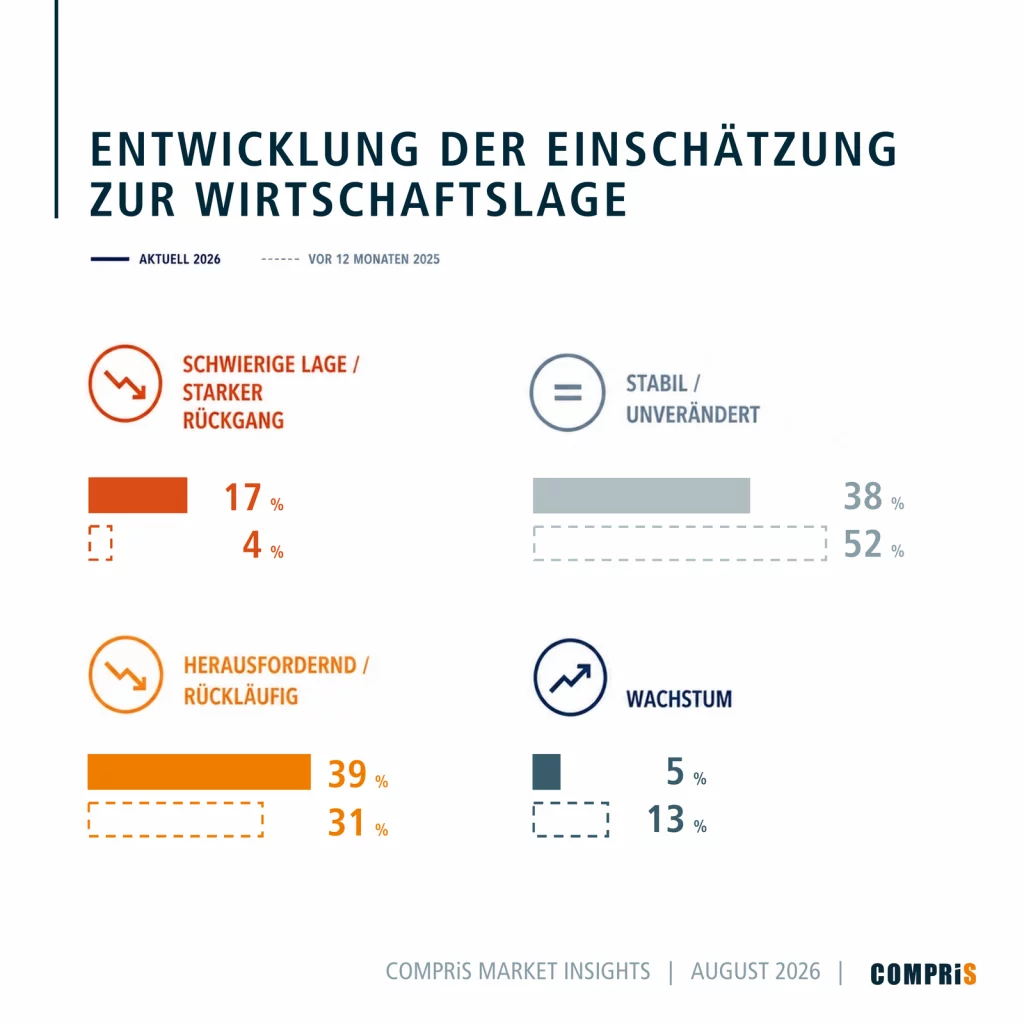
A comparison with the results from 2025 shows a clear shift toward more cautious market assessments. The share of companies with stable valuations fell from 52% to 38%, while the share of companies facing difficult business conditions more than quadrupled, rising from 4% to 17 %. At the same time, the share of growing companies declined from 13% to 5%.
For Vendor , this means: Projects are evaluated more critically, investments are prioritized more strictly, and partners expect concrete added value in terms of cost-effectiveness, delivery capability, and sales support.
End Customers' Investment Priorities: Operations & Risk Mitigation Rather Than Innovation
Despite the challenging economic situation, end customers continue to invest in their IT. However, priorities are shifting significantly: The focus is now on ensuring IT operations, cybersecurity, and optimizing existing environments. Investments in innovative, forward-looking areas are being made much more selectively.
Feedback from IT system integrators regarding COMPRiS:
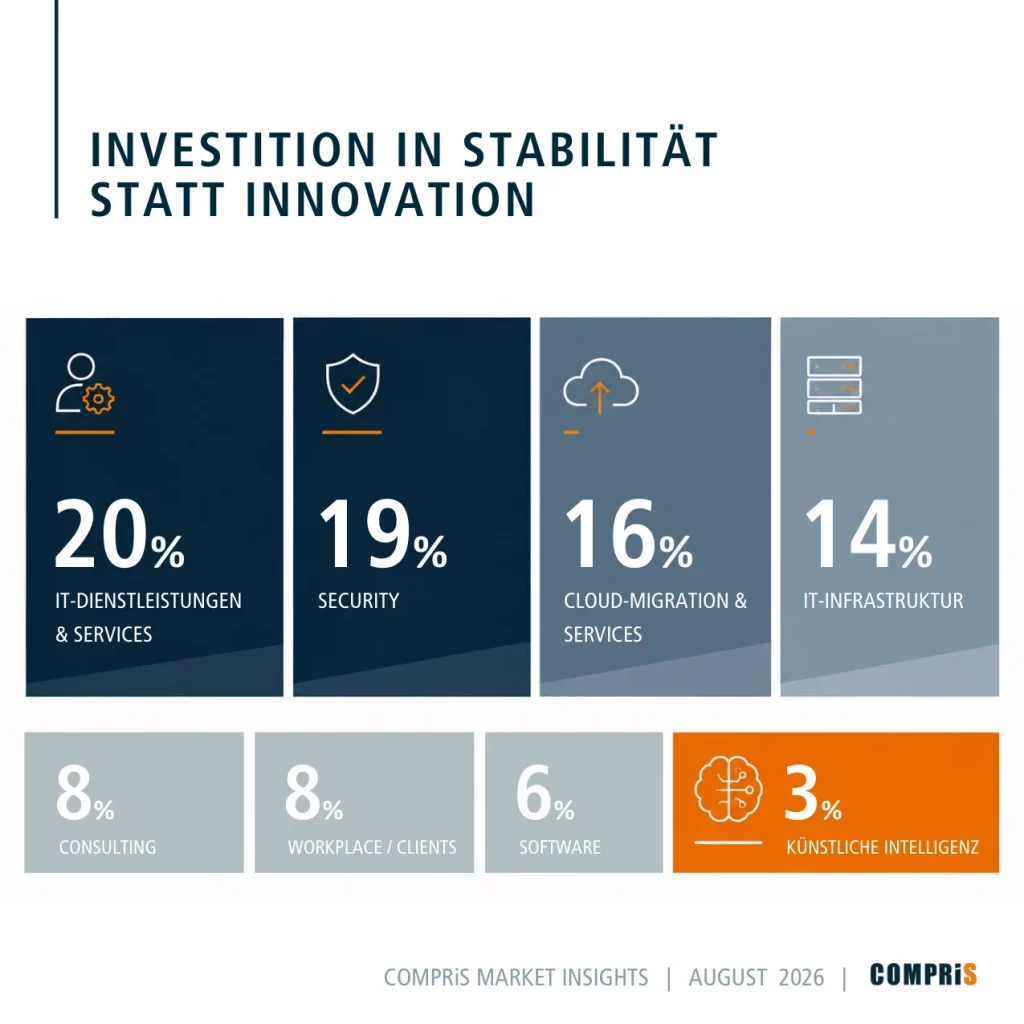
IT services (optimization, maintenance, operation, support) account for 20% of current investments.
19% on security (firewall, endpoint security, anti-spyware).
16% on cloud migration and cloud services (IaaS, PaaS, SaaS).
14% on IT infrastructure (servers, storage, network, data center).
Other areas mentioned, though with significantly lower demand, include consulting (8%), workplace/clients (8%), application software (6%), and artificial intelligence, at just 3%.
As a result, many IT service providers are currently clearly focusing on “ensuring and optimizing operations” rather than on innovation projects.
OUR CONCLUSION
Double Pressure: Economic Conditions Compound Supply Chain Bottlenecks
The latest findings on the economic situation can be directly linked to our previous Market Insights survey on component shortages (December 2025–March 2026), and together they paint an insightful picture of the current state of the channel.
The component shortage study had already shown that 88% of system integrators and IT service providers were affected by supply shortages in the server and storage sectors—with noticeable consequences such as project delays (24%) and longer sales cycles (17%). The latest economic data confirms and reinforces this picture: Despite investments in IT infrastructure (16%), economic sentiment has deteriorated year-over-year.
Taken together, the two surveys reveal a consistent pattern: The IT channel is currently facing dual pressures in the IT infrastructure business —on the one hand, from operational supply chain issues, and on the other, from a deteriorating overall economic situation. These two effects reinforce each other: Component shortages increase the workload and slow down projects (for example, 45% of partners in the shortage study reported higher effort in preparing proposals due to the need to evaluate substitute products), while the weaker economic situation simultaneously dampens end customers’ willingness to invest. The result is a period of heightened uncertainty in which both delivery capability and the investment climate jointly determine project success and revenue growth within the channel.
Many IT service providers are currently stepping up their efforts to evaluate alternative Vendor and vendors. Key factors include, in particular, delivery capability, value for money, and the long-term reliability of Vendor. At the same time, partners are observing growing sensitivity among end customers regarding costs, availability, and investment security.

Anyone who wants to succeed in the channel today must be able to do two things at once: deliver reliably and offer compelling value. The promise of innovation alone isn't enough right now.
GERALD HOLLER - Managing Director COMPRiS GMBH
Market Insights as a Compass for the Channel
With COMPRiS Market Insights, we provide manufacturers and channel managers with a fact-based perspective on how system integrators and IT service providers are experiencing current market changes—from component shortages and the economic situation to AI-driven portfolio development. Based on these insights, we help our clients tailor their go-to-market strategies, partner programs, and sales execution to address their partners’ real pain points.
Those who understand the perspective of their channel partners and their end customers can not only manage bottlenecks but also turn them into opportunities for growth and differentiation.
The results are based on a COMPRiS Market Insights survey of 326 IT service providers, system houses, and system integrators in Germany and Austria, conducted between May and July 2026.
The survey included managing directors, sales managers, and those responsible for vendor selection, procurement, and portfolio management.
COMPRiS Market Insights regularly provides data-driven insights into market trends, maturity levels, and challenges in indirect sales and the channel environment.
holistic or selectively?
We support you throughout the entire sales process
You decide on the right mix: from individual, clear and short-term projects to complete sales and budget responsibility for defined segments. From strategy and identifying potential to onboarding and supporting new customers and partners.